Revocable vs Irrevocable Trust in Illinois: An Overview
Serving McHenry, Lake, and Kane
Counties for Over 40 Years
Explore the benefits of revocable vs irrevocable trusts in Illinois with Diamond Legal, PC, and learn how to protect your legacy and secure your family’s future.

“The Diamond Legal team was outstanding! Every single person that works at that firm that I worked with was supportive, kind and understanding. I would get calls out of the blue with an update of where we were in the process, as well as confirming if I had any questions or needed any support.” I always felt like they were on my side.”
– Cherie Stanford
Revocable vs Irrevocable Trust in Illinois: Key Differences
Trusts are powerful legal tools that go far beyond simply transferring assets. For over 40 years, Diamond Legal, PC has helped families in McHenry and Lake County navigate the complexities of estate planning, always focusing on clarity and compassion. A comprehensive trust strategy can protect your legacy, provide for loved ones, and offer genuine peace of mind.
Essentially, a trust is a legal arrangement where you (the grantor) place assets under the care of a trustee, who manages them for your chosen beneficiaries. While this concept may sound straightforward, the flexibility trusts offer can be invaluable. Depending on your unique goals, a trust can help you:
- Avoid probate, saving time and money for your heirs
- Provide for family members with special needs without jeopardizing government benefits
- Protect assets from potential lawsuits or creditors
- Minimize estate taxes
- Ensure professional management of assets for beneficiaries who may not be financially savvy
We’ve seen trusts bring tangible benefits to all kinds of clients. For instance, we recently guided a local business owner in creating a trust that safeguarded his company’s assets and ensured a smooth transition to his children upon retirement. This proactive planning allowed him to focus on enjoying his life’s work without worry.
Not all trusts are the same, which is why we always take time to discuss your family dynamics, finances, and personal wishes before recommending a strategy. Common types of trusts include:
- Revocable Living Trusts
- Irrevocable Trusts
- Special Needs Trusts
- Charitable Trusts
Each type serves a specific purpose. As you consider your estate planning goals, keep in mind that the right trust should reflect your long-term vision.
At Diamond Legal, we’re here to simplify what might initially seem daunting. Whether you’re looking to protect assets, care for loved ones with special needs, or plan a smooth business transition, we’ll craft a trust solution that addresses your objectives and reflects your personal values.
What Is a Revocable Trust?
A revocable trust (often called a living trust) offers a flexible way to manage your assets during your lifetime and provide for a seamless transfer after you pass away. When you establish a revocable trust, you transfer ownership of your assets into the trust but retain the power to modify or even dissolve it whenever you choose.
Key features of a revocable trust include:
- Flexibility: You can add or remove assets, change beneficiaries, or revoke the trust entirely.
- Control: You typically serve as trustee and maintain control of your assets while you are able.
- Privacy: Trusts generally avoid probate, which keeps the details of your estate out of the public record.
- Continuity: If you become incapacitated, a successor trustee can automatically step in to manage the trust on your behalf.
Why consider setting up a revocable trust? Bypassing probate is particularly advantageous if you wish to save your beneficiaries time and money. Keeping your affairs private is another common goal. These trusts can also handle asset management should you become incapacitated—an aspect many families find reassuring. While revocable trusts don’t provide direct income or estate tax benefits during your lifetime, they can still be structured to reduce estate taxes down the road.
Because everyone’s situation is unique, we work closely with you to determine if a revocable trust is the ideal fit. At Diamond Legal, we look at the size of your estate, your family relationships, and your wishes for the future. If you are a business owner, a revocable trust can help protect your company by outlining how it should transition if you step away or pass on.

What Is an Irrevocable Trust?
An irrevocable trust is more rigid than a revocable trust, but that rigidity comes with significant advantages in terms of asset protection and tax benefits. When you set up an irrevocable trust, you generally cannot change or dissolve it unless the beneficiaries—and sometimes the courts—provide permission.
Main characteristics of an irrevocable trust include:
- Asset Protection: Assets in an irrevocable trust are no longer considered part of your personal estate, making them more secure from lawsuits and creditors.
- Tax Benefits: Because assets move out of your taxable estate, you may reduce estate taxes and potentially certain income taxes, depending on how the trust is structured.
- Control Over Distribution: You can set precise terms for how and when beneficiaries receive assets.
- Medicaid Planning: In certain situations, an irrevocable trust can help with Medicaid eligibility and protect family assets for the next generation.
In our experience, an irrevocable trust may be the better choice if you have a larger estate, work in a high-risk profession, or need robust asset protection. It can also be suitable for families with special needs beneficiaries or those focusing on Medicaid planning. We’ve guided many clients in McHenry and Lake County through establishing irrevocable trusts, making sure their trusts are structured correctly to meet their long-term goals.

Key Differences Between Revocable and Irrevocable Trusts
We often receive questions about how these two types of trusts differ. Here are the main distinctions:
- Control and Flexibility: A revocable trust lets you retain control and make changes anytime. An irrevocable trust essentially cannot be altered once established.
- Asset Protection: Revocable trusts generally do not protect you from creditors or lawsuits because you still effectively own the assets. Irrevocable trusts, by contrast, remove assets from your personal ownership and can offer substantial protection.
- Tax Implications: Assets in a revocable trust typically remain part of your taxable estate. In an irrevocable trust, they are considered separate, offering potential tax advantages.
- Probate Avoidance: Both can help avoid probate, but they do so in different ways. Revocable trusts transfer assets efficiently at death, while irrevocable trusts remove assets entirely from your estate.
- Medicaid Considerations: Irrevocable trusts can be helpful for Medicaid planning, whereas revocable trusts do not offer protection when applying for government benefits.
Deciding which trust is right for you depends on a host of factors, including your tolerance for risk, the size of your estate, and the level of flexibility you’d like to maintain. At Diamond Legal, we help you weigh each factor, ensuring you know exactly how your choice aligns with your financial and personal goals.
Benefits of Revocable Trusts
Many individuals opt for revocable trusts because of their flexibility and straightforward management. Here are some advantages to keep in mind:
- Ease of Management: You can modify the trust without court involvement and retain full control of your assets.
- Flexibility to Amend: If your personal or financial situation changes, you can adapt your trust accordingly.
- Privacy Protection: Unlike wills, which are public after probate, your trust remains private.
- Probate Avoidance: Assets transfer to beneficiaries without the extra cost and time probate often requires.
- Seamless Transition of Management: If you become incapacitated, a successor trustee can easily step in and follow your instructions.
At Diamond Legal, we often explain to our clients that this type of trust is especially appealing when you want to retain control but still streamline inheritance matters. A revocable trust can also give business owners peace of mind, particularly in industries where day-to-day operations need to continue seamlessly, even if the owner becomes unavailable.
Benefits of Irrevocable Trusts

By placing your assets in an irrevocable trust, you build a strong layer of protection that can shield them from creditors, lawsuits, and even certain taxes. Below are a few key benefits:
- Superior Asset Protection: Because you relinquish ownership, assets become significantly less vulnerable to claims.
- Tax Advantages: Irrevocable trusts can reduce estate taxes by removing assets from your taxable estate.
- Distribution Control: You can set strict parameters for how beneficiaries will receive assets, ensuring your wishes are carried out.
- Medicaid Eligibility: Placing assets in an irrevocable trust may preserve them while potentially helping you qualify for Medicaid after a look-back period.
We’ve seen firsthand how families in McHenry and Lake County use irrevocable trusts to protect loved ones, particularly if they’re concerned about passing assets to children or grandchildren without burdensome tax consequences. With the right guidance, you can customize an irrevocable trust to align with your family’s specific needs.
Potential Drawbacks of Revocable Trusts
Although revocable trusts come with many advantages, they also have certain drawbacks:
- Limited Asset Protection: Since you keep control of the assets, they are not shielded from lawsuits or creditors.
- Ongoing Administrative Responsibilities: You should retitle assets into the trust and keep them updated. If you fail to “fund” the trust properly, some property might still pass through probate.
- No Direct Tax Benefits: During your lifetime, assets remain part of your taxable estate.
- Potential for Family Conflict: Because you can change the trust at any time, disputes may arise if beneficiaries worry about frequent amendments.
- Costs and Complexity: While simpler than some legal tools, revocable trusts can still be more costly to set up than a basic will.
These considerations don’t negate the value of a revocable trust but do highlight the importance of thorough planning. Our goal is to help you decide if these limitations are manageable based on your circumstances. We’ll guide you through the administrative aspects and ensure you understand the trust’s mechanics so you can enjoy the peace of mind it provides.
Potential Drawbacks of Irrevocable Trusts

Irrevocable trusts, while beneficial, are not without trade-offs:
- Lack of Flexibility: Altering or revoking these trusts is generally prohibited once they’re established.
- Complex Setup and Funding: Creating and properly funding an irrevocable trust can be time-consuming. Mistakes in the process may have lasting repercussions.
- Permanence of Asset Transfer: You lose direct control over assets after placing them in the trust, which can be psychologically challenging.
- Ongoing Management: Trustees should handle investment and distribution decisions carefully, often requiring professional oversight.
- Potential Tax Complexity: While the trust may reduce estate taxes, it could trigger higher trust income taxes if not structured properly.
We work closely with our clients to ensure an irrevocable trust is set up correctly from the start. Because undoing one is difficult, it’s crucial to weigh the pros and cons before making the commitment. At Diamond Legal, we take the time to tailor each trust so that you feel confident about every detail.
Choosing the Right Trust for Your Situation
When deciding between a revocable and an irrevocable trust—or exploring other trust options—there is no one-size-fits-all solution. Consider the following factors:
- Your family’s dynamics and long-term goals
- The size and complexity of your estate
- Your desire for asset protection versus control
- Potential tax implications
- Business succession and continuity needs
At Diamond Legal, we bring over four decades of experience in crafting customized estate plans for individuals and families in McHenry and Lake County. We review each client’s financial situation, personal concerns, and future aspirations before recommending a trust structure.
Whether you’re leaning toward a revocable trust, an irrevocable trust, or another specialized vehicle, we’ll make sure you understand every implication so you can move forward with clarity and confidence.

Get Professional Guidance on Your Estate Planning Needs
Revocable and irrevocable trusts each play a vital role in estate planning, but choosing the right one involves a careful look at your goals, family dynamics, and risk tolerance. Our team at Diamond Legal is dedicated to making these complex decisions more approachable by offering personalized advice rooted in decades of hands-on experience.
If you’d like to discuss how a revocable trust, an irrevocable trust, or another estate planning tool might fit your unique circumstances, we invite you to contact us at Diamond Legal. Let’s work together to secure what matters most to you and your family, so you can move forward with peace of mind.
Frequently Asked Questions: Revocable vs. Irrevocable Trusts in Illinois
Can a revocable trust protect my assets from a lawsuit or nursing home costs?
Generally, no. Because you retain the power to amend or revoke a revocable living trust, the law views those assets as being within your control. Therefore, they are typically reachable by creditors, subject to legal judgments, and counted as available resources when determining Medicaid eligibility for long-term care.
How does an irrevocable trust assist with Illinois Medicaid planning?
An irrevocable trust is often used to start the “look-back period” for Medicaid eligibility. In Illinois, there is a 60-month (five-year) look-back period. If you transfer assets into a properly structured irrevocable trust at least five years before applying for Medicaid, those assets are generally not counted toward your $2,000 asset limit, effectively “shielding” them for your heirs.
What is the “funding” process for an Illinois trust?
A trust is only effective if it actually holds title to your property. “Funding” involves the formal legal process of re-titling assets—such as your home, bank accounts, or brokerage accounts—from your individual name into the name of the trust (e.g., “The [Name] Revocable Living Trust”). If an asset is left outside the trust and exceeds the $150,000 small estate threshold, it may still be forced through probate.
Who can serve as a trustee for an irrevocable trust in Illinois?
While you can often be the trustee of your own revocable trust, you typically cannot be the sole trustee of your own irrevocable trust if you want to gain tax and asset protection benefits. Most grantors appoint an adult child, a trusted friend, or a corporate fiduciary (like a bank) to manage the assets according to the strict terms laid out in the trust document.
Are there specific tax filings required for trusts in Illinois?
A revocable living trust is a “grantor trust,” meaning it uses your Social Security number and does not require a separate tax return while you are alive. However, an irrevocable trust often obtains its own Employer Identification Number (EIN) and may be required to file IRS Form 1041 and Illinois Form IL-1041 if it generates more than a certain amount of annual income.
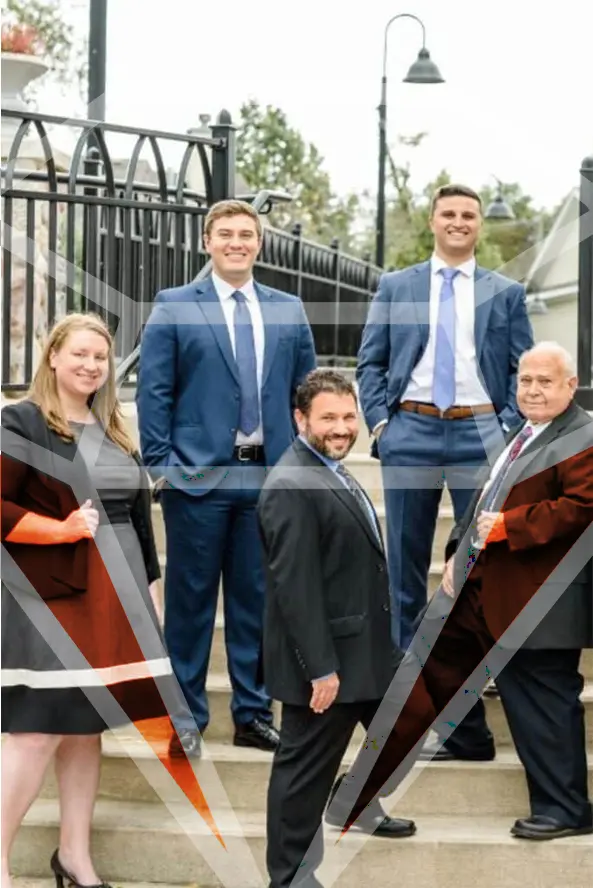
Our team is here for one reason: you.
The Diamond Legal Team
We’re ready to help you rebuild your life.
Parting ways with your spouse is overwhelming, confusing and exhausting.
One way or another, you have to move forward with your life.
The team at Diamond Divorce Law has been there, and we get it. That’s why we are passionate about guiding others through this difficult time. We’ve helped hundreds of clients navigate the divorce process, custody battles, and other family law issues. We always find the way for our clients to move forward and rebuild their life.
Our process is streamlined, informative, and communicative.
We strive to produce the best possible outcome for you, your children, and your finances.
If you’re ready to move forward with your life, give us a call today.
Frequently Asked Questions: Revocable vs. Irrevocable Trusts in Illinois
Can a revocable trust protect my assets from a lawsuit or nursing home costs?
Generally, no. Because you retain the power to amend or revoke a revocable living trust, the law views those assets as being within your control. Therefore, they are typically reachable by creditors, subject to legal judgments, and counted as available resources when determining Medicaid eligibility for long-term care.
How does an irrevocable trust assist with Illinois Medicaid planning?
An irrevocable trust is often used to start the “look-back period” for Medicaid eligibility. In Illinois, there is a 60-month (five-year) look-back period. If you transfer assets into a properly structured irrevocable trust at least five years before applying for Medicaid, those assets are generally not counted toward your $2,000 asset limit, effectively “shielding” them for your heirs.
What is the “funding” process for an Illinois trust?
A trust is only effective if it actually holds title to your property. “Funding” involves the formal legal process of re-titling assets—such as your home, bank accounts, or brokerage accounts—from your individual name into the name of the trust (e.g., “The [Name] Revocable Living Trust”). If an asset is left outside the trust and exceeds the $150,000 small estate threshold, it may still be forced through probate.
Who can serve as a trustee for an irrevocable trust in Illinois?
While you can often be the trustee of your own revocable trust, you typically cannot be the sole trustee of your own irrevocable trust if you want to gain tax and asset protection benefits. Most grantors appoint an adult child, a trusted friend, or a corporate fiduciary (like a bank) to manage the assets according to the strict terms laid out in the trust document.
Are there specific tax filings required for trusts in Illinois?
A revocable living trust is a “grantor trust,” meaning it uses your Social Security number and does not require a separate tax return while you are alive. However, an irrevocable trust often obtains its own Employer Identification Number (EIN) and may be required to file IRS Form 1041 and Illinois Form IL-1041 if it generates more than a certain amount of annual income.